 Analysis by Appwee
I’d be cautious about treating any credit-building app as a shortcut. Kikoff - Build Credit Quickly is best approached as a structured way to establish a payment routine, not a promise of a particular score or a quick route to a loan. The useful question is whether its approach fits your finances and habits, and whether you can keep up with the payments without taking on obligations you do not need.
What free access means in practice
Kikoff is a free finance app from Kikoff Inc., so trying the app does not require an upfront purchase. That is a meaningful starting point for someone comparing credit-building options, especially if a deposit or a new card would be difficult to manage. I would still separate “free to download” from “free in every possible sense”: before agreeing to any credit product or payment arrangement, read the terms shown in the app and check whether the specific option you select has costs or conditions.
The app has an Everyone content rating and supports Android 7.0 or later. Its current version is 1.158.2511. Those details help with basic device and household suitability, but the more important test is whether the product’s repayment structure makes sense for your budget. An app can be free to install while the financial commitment inside it still deserves careful attention.
How I would judge the value
The potential value is not a pile of financial tools; it is the chance to build a repeatable credit habit through an app-based credit product. That may be useful if you have little credit history, want a more guided alternative to shopping for a conventional card, or find paperwork-heavy options intimidating. The app’s scale also gives some context: it has over a million installs, around 115,000 ratings, and a 4.8 average. I treat that as a sign of broad interest, not proof that every user will see the same result.
For a realistic example, imagine you are preparing to rent a new place and realize your credit file is thin. You could use Kikoff to learn the rhythm of making scheduled payments while keeping your everyday spending separate from a traditional credit card. The practical benefit is the routine and the chance to add positive activity, not an assurance that a landlord, lender, or credit bureau will respond in a particular way. Credit outcomes depend on more than one app.
Tradeoffs to consider before you start
Credit building takes time, and regular payments only help if you can afford to make them consistently. I would first look at your monthly bills and decide whether an additional payment fits comfortably, rather than signing up because the idea of improving credit feels urgent. A missed or poorly managed obligation can work against the careful habits you are trying to establish, so a smaller commitment you can maintain is better than an ambitious one that strains your budget.
There is also a difference between tracking progress and controlling the factors behind a credit score. A score view can make change easier to notice, but it does not replace checking your credit reports for errors, keeping existing accounts in good standing, or planning around future borrowing. If your immediate problem is an incorrect report entry, a billing dispute, or debt that is already difficult to repay, an app-based credit-building routine may not address the main issue. In those situations, I would prioritize resolving the underlying problem first.
More From Our Writers

OTR Makes Off-Road Roaming a Perfect Fit for Short Play Sessions

Prime Video vs. Netflix and Disney+: More Choice, More Clutter

SHAREit Review: A Fast, No-Cloud Way to Move Files

Cryptoguru Makes Crypto Trading Safer, but Can It Teach Restraint?

FC Mobile 26 Turns Soccer into a Season-Long Service

Reddit Is Worth Your Time Only If You Choose Your Communities
Who is likely to get the most from it
I can see Kikoff suiting someone who wants a guided first step and values keeping credit-building activity apart from day-to-day card purchases. It may also appeal to people who prefer handling a simple routine on a phone instead of comparing several card applications. Before beginning, I would make a small checklist: confirm the payment schedule, understand the product terms, choose a reminder method, and decide how you will review progress without obsessing over every short-term score movement.
It is less compelling if you already have a well-managed credit card that reports activity and you are comfortable using it responsibly. In that case, adding another account may create complexity without solving a real gap. It may also be the wrong fit if you need immediate cash, want a general-purpose line of credit for purchases, or cannot reliably meet another payment. Kikoff is aimed at credit building; it should not be mistaken for emergency financing or a substitute for a budget.
Compared with a secured credit card, the experience is more focused on an app-led credit-building path rather than using a deposit-backed card for everyday purchases. A secured card can make more sense if you specifically want a payment card and can set aside the required deposit. A conventional card may be more useful for someone with established credit who wants flexible spending and can avoid carrying a balance. Neither alternative is automatically better: the right choice depends on whether your priority is a guided routine, access to a card, or broader purchasing flexibility.
One useful habit is to treat the first few weeks as a setup period rather than a score race. Read each screen before accepting an option, note when payments are due, and set a calendar reminder even if the app also displays account information. If you already use a budgeting app or bank calendar, put the payment there too. A second reminder is a simple safeguard against relying on memory, especially when a new financial task is competing with rent, utilities, and other regular bills.
The Magic Behind Kikoff
So, what’s the buzz about Kikoff? It's an app designed with one purpose: helping you build or improve your credit score as efficiently as possible. The app is super user-friendly, and you don’t need to be a financial wizard to get started. You sign up, and bam—you're on your way to a healthier credit score.
Easy Setup and User Experience
Getting started with Kikoff is as easy as pie. Once you download the app, it greets you with a sleek, intuitive interface that guides you through the setup process. You won’t find yourself lost in a maze of confusing menus or jargon-heavy text. And honestly, who has time for that?
The app offers a clear step-by-step guide that walks you through linking your bank account and setting up your credit line. You can do it all in just a few taps. No fuss, no headaches. And if you're anything like me, you’ll appreciate not having to hunt down your old credit reports or dig through piles of paperwork.
A Unique Approach to Building Credit
Kikoff's strategy for boosting your credit score is pretty unique. Instead of traditional credit cards or loans, Kikoff offers a line of credit that you can use within their store to purchase digital products. You make small payments over time, and these payments are reported to the credit bureaus. It’s like a gym membership for your credit score, where regular, consistent activity gets you results.
What I love most about this approach is that it’s low-risk. You're not racking up debt or paying high-interest rates, making it ideal for those new to credit or looking to repair their financial standing. Plus, there are no hidden fees or unexpected charges. What you see is what you get.
Tracking Progress
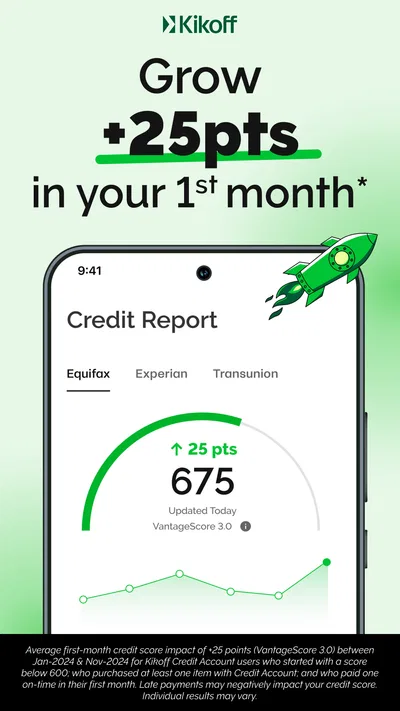
In the world of credit building, patience is a virtue, but who says you can’t enjoy the ride? Kikoff keeps you motivated by letting you track your credit score and see how your actions are making a difference. The app provides insights into your credit performance, and it’s super satisfying to see those numbers climb. It’s like watching your savings account grow, but with more excitement!
And if you're a data nerd like me, you’ll appreciate the detailed breakdowns of your credit activity. It's like having a personal financial advisor giving you tips on what’s working and what needs a little tweak.
Security and Support
Now, let's talk security. When dealing with finance apps, this is where I get a bit twitchy, but Kikoff doesn't disappoint. It uses bank-level encryption to keep your data safe, which means you can breathe easy knowing your info is locked down tighter than Fort Knox.
If you ever hit a snag or have a burning question, Kikoff’s customer support is just a tap away. They’re quick to respond and genuinely helpful, which is a huge plus in my book. No one likes being stuck in a loop of automated responses, right?
Final Thoughts: Is Kikoff Worth It?
In a nutshell, Kikoff - Build Credit Quickly is a solid choice for anyone looking to improve their credit score without the hassle of traditional methods. It’s straightforward, effective, and most importantly, it works without putting you in financial jeopardy. Whether you're starting from scratch or trying to bounce back from past financial hiccups, Kikoff offers a lifeline to better credit.
So, if you're ready to take control of your financial future, give Kikoff a whirl. You’ll be on your way to a better credit score in no time, and who knows, maybe even a new car or house is waiting just around the corner. Cheers to building credit the smart way!
Kikoff - Build Credit Quickly Pros and Cons
- User-friendly interface for beginners.
- No credit check required to start.
- Low monthly fee for services.
- Free educational resources included.
- Tracks progress towards credit goals.
- Limited to U.S. residents only.
- No physical credit card offered.
- Customer support via email only.
- Not suitable for immediate credit needs.
- Requires bank account linking.
Kikoff - Build Credit Quickly Frequently Asked Questions
What is Kikoff and how does it help build credit?
Kikoff is a financial app designed to help users build their credit quickly and effectively. It offers a credit line that you can use to make small purchases. By paying off these purchases on time, you can gradually increase your credit score. Kikoff reports your payment history to major credit bureaus, making it an ideal tool for credit building.
Is Kikoff safe to use for financial transactions?
Yes, Kikoff is safe to use. The app employs robust security measures, including encryption and secure authentication, to protect users' financial and personal data. Additionally, Kikoff is designed with transparency in mind, ensuring that users clearly understand how their data is used and reported to credit bureaus.
How much does it cost to use Kikoff?
Kikoff offers a subscription model with a low monthly fee. This fee grants access to a credit line and other financial tools within the app. There are no hidden charges or interest fees, making it an affordable option for those looking to improve their credit score without incurring significant costs.
Can Kikoff actually improve my credit score?
Yes, Kikoff can help improve your credit score. By using the app to make purchases and consistently paying them off on time, you create a positive payment history. Kikoff reports these activities to major credit bureaus, which can lead to an increase in your credit score over time, especially if you are new to credit or rebuilding your score.
What sets Kikoff apart from other credit-building apps?
Kikoff stands out due to its simplicity and low cost. Unlike many other credit-building tools, Kikoff does not charge interest or additional fees beyond its basic subscription. The app is user-friendly and designed specifically for those new to credit building, making it accessible and straightforward for users at any stage of their credit journey.
Gallery